You stay the homeowner
A reverse mortgage does not transfer title to the lender. You remain responsible for property taxes, homeowners insurance, property upkeep, and other loan requirements.
A reverse mortgage is a special type of home loan for eligible homeowners age 62 and older. It allows you to access a portion of your home equity without selling your home.
With an FHA-insured Home Equity Conversion Mortgage (HECM), you generally do not have to make monthly principal-and-interest payments. Interest and fees accrue, so the loan balance typically increases over time. You must continue paying property taxes and homeowners insurance, maintaining your home, and meeting the loan terms.
A reverse mortgage is not right for everyone. Eligibility, costs, counseling, and repayment rules apply.
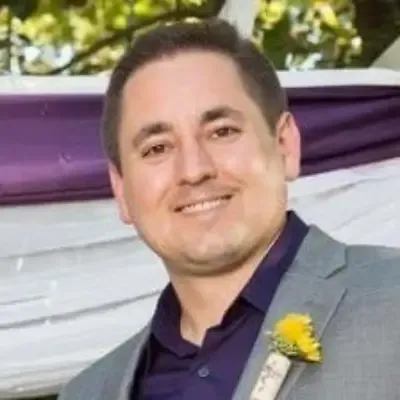
With many years of experience in mortgage lending, Mike has helped homeowners navigate important financial decisions with clarity and care.
A reverse mortgage isn’t right for everyone. My goal is to help you and your family understand your options, answer your questions, and determine whether it makes sense for your retirement plans.
You’ll work directly with me—not a call center.
Mike Graves NMLS# 1992057.
Schedule a ConversationA reverse mortgage lets eligible homeowners convert a portion of their home equity into funds while continuing to live in the home, as long as loan obligations are met.
You continue living in the home and keep ownership, provided you meet the loan terms.
Instead, the loan balance typically grows over time as interest and fees accrue.
You must keep the home as your primary residence, maintain it, and stay current on taxes and insurance.
Reverse mortgages can raise important questions for the whole family. We welcome adult children and trusted family members in the conversation—with the homeowner's permission.
Eligibility and available proceeds depend on age, home value, interest rates, existing liens, program limits, and financial assessment.
It’s important to understand both the opportunities and the responsibilities before deciding whether a reverse mortgage is right for your family.
A reverse mortgage does not transfer title to the lender. You remain responsible for property taxes, homeowners insurance, property upkeep, and other loan requirements.
For eligible borrowers who meet loan obligations, monthly principal and interest payments are not required. Interest and fees accrue, increasing the loan balance over time.
Depending on eligibility and HECM program rules, funds may be available through a line of credit, monthly payments, a lump sum, or a combination.
FHA-insured Home Equity Conversion Mortgages require counseling from an approved independent HECM counselor. Upfront and ongoing costs should be reviewed carefully.
No—not automatically. A reverse mortgage does not transfer ownership of the home to the lender. When the loan becomes due, heirs may have options to keep the home by repaying the debt, sell the home and retain any remaining equity, or allow the lender to resolve the debt under applicable rules.
For an FHA-insured HECM, eligible heirs may generally satisfy the loan for the lesser of the outstanding loan balance or 95% of the home’s current appraised value, subject to program rules. HECMs are generally non-recourse, meaning heirs are not personally responsible for a shortfall beyond the home’s value.
Repayment is generally triggered when the last borrower dies, sells, or permanently moves out, subject to protections for eligible non-borrowing spouses and other program rules. Heirs must meet applicable timelines.
I encourage homeowners to include their adult children in the discussion, if they wish. My job is to help your family understand the benefits, costs, responsibilities, and long-term implications before making a decision.
If you want to understand the basics, compare options, or include family members in the discussion, we are happy to help you take the next step at a comfortable pace.
Share a few details and our team will follow up.
No. You retain title, subject to the mortgage lien and loan terms, as long as you meet your obligations.
A HECM generally does not require monthly principal-and-interest payments, but you remain responsible for property taxes, homeowners insurance, maintenance, and any applicable charges. Failure to meet obligations may cause the loan to become due and payable.
The loan generally becomes due when the last borrower permanently leaves the home, sells it, dies, or another maturity event occurs. Eligible non-borrowing spouses may have certain protections. Heirs may sell the home, repay the loan, or consider other available options, subject to applicable rules.
Yes, subject to resolving the reverse mortgage debt. Any remaining equity after the loan is repaid belongs to the homeowner or estate. FHA-insured HECMs are generally nonrecourse loans, subject to program rules.
No. Closing costs, mortgage insurance premiums, servicing charges when applicable, and accruing interest can increase the loan balance. We can explain estimated costs and compare alternatives.
Yes. HECM borrowers must receive independent counseling from a HUD-approved HECM counselor before proceeding.
Absolutely. We welcome family members and encourage open conversations so everyone understands the options. Adult children or trusted relatives can join with the homeowner's permission.
Whether you are just beginning to explore reverse mortgages or already have specific questions, we are here to help you understand your options in plain language.